The Fascinating Psychology Behind a Single Trade That Triggers an Unexpected Selling Spree
Have you ever noticed something strange about your investment decisions?
You open your brokerage account intending to sell just one profitable stock.
You execute the trade, lock in a nice profit, and feel satisfied.
But something unexpected happens.
You start looking at your other investments. Suddenly, you feel tempted to sell another profitable position. Then another. And perhaps one more.
Before you realize it, you’ve sold half your portfolio—even though you originally intended to sell just one stock.
Interestingly, nothing significant may have changed in the financial markets during those few minutes.
The valuations of your other stocks haven’t changed. Their business prospects haven’t changed. Your original investment thesis hasn’t changed.
The only thing that has changed is your psychological state.
Why does this happen?
Behavioral finance offers several fascinating explanations.
1. Decision Momentum: Once You Start, It’s Easier to Continue
One possible explanation is decision momentum.
Before selling your first stock, your mind is in what we might call holding mode.
You’re comfortable with your investments. You’re not actively considering selling anything.
But the moment you execute your first sale, something changes.
You’ve entered decision-making mode.
Suddenly, you start evaluating your other positions.
“Should I sell this one too?”
“This stock has appreciated substantially. Maybe I should take some profits.”
“I’m already reducing my exposure. Perhaps I should reduce it further.”
The first action appears to make subsequent actions psychologically easier.
Think about what happens when you decide to clean one drawer in your house.
Initially, you intend to organize just that drawer.
But after finishing, you notice another messy drawer.
Then another.
Before long, you’re reorganizing the entire room.
What began as a single action has created momentum for additional actions.
Something similar can happen when managing investments.
It’s important to recognize that decision momentum is a possible psychological explanation, not proof that every sequence of trades has the same underlying cause.
2. Status Quo Bias: The First Sale Breaks Psychological Inertia
Humans naturally prefer maintaining their existing circumstances.
Psychologists call this tendency status quo bias.
When you own ten stocks, doing nothing is psychologically easy.
Selling requires an active decision.
You must evaluate the investment, consider the consequences, and overcome the uncertainty of making a change.
But once you’ve sold your first stock, you’ve already broken that psychological inertia.
The barrier to selling another position may feel smaller.
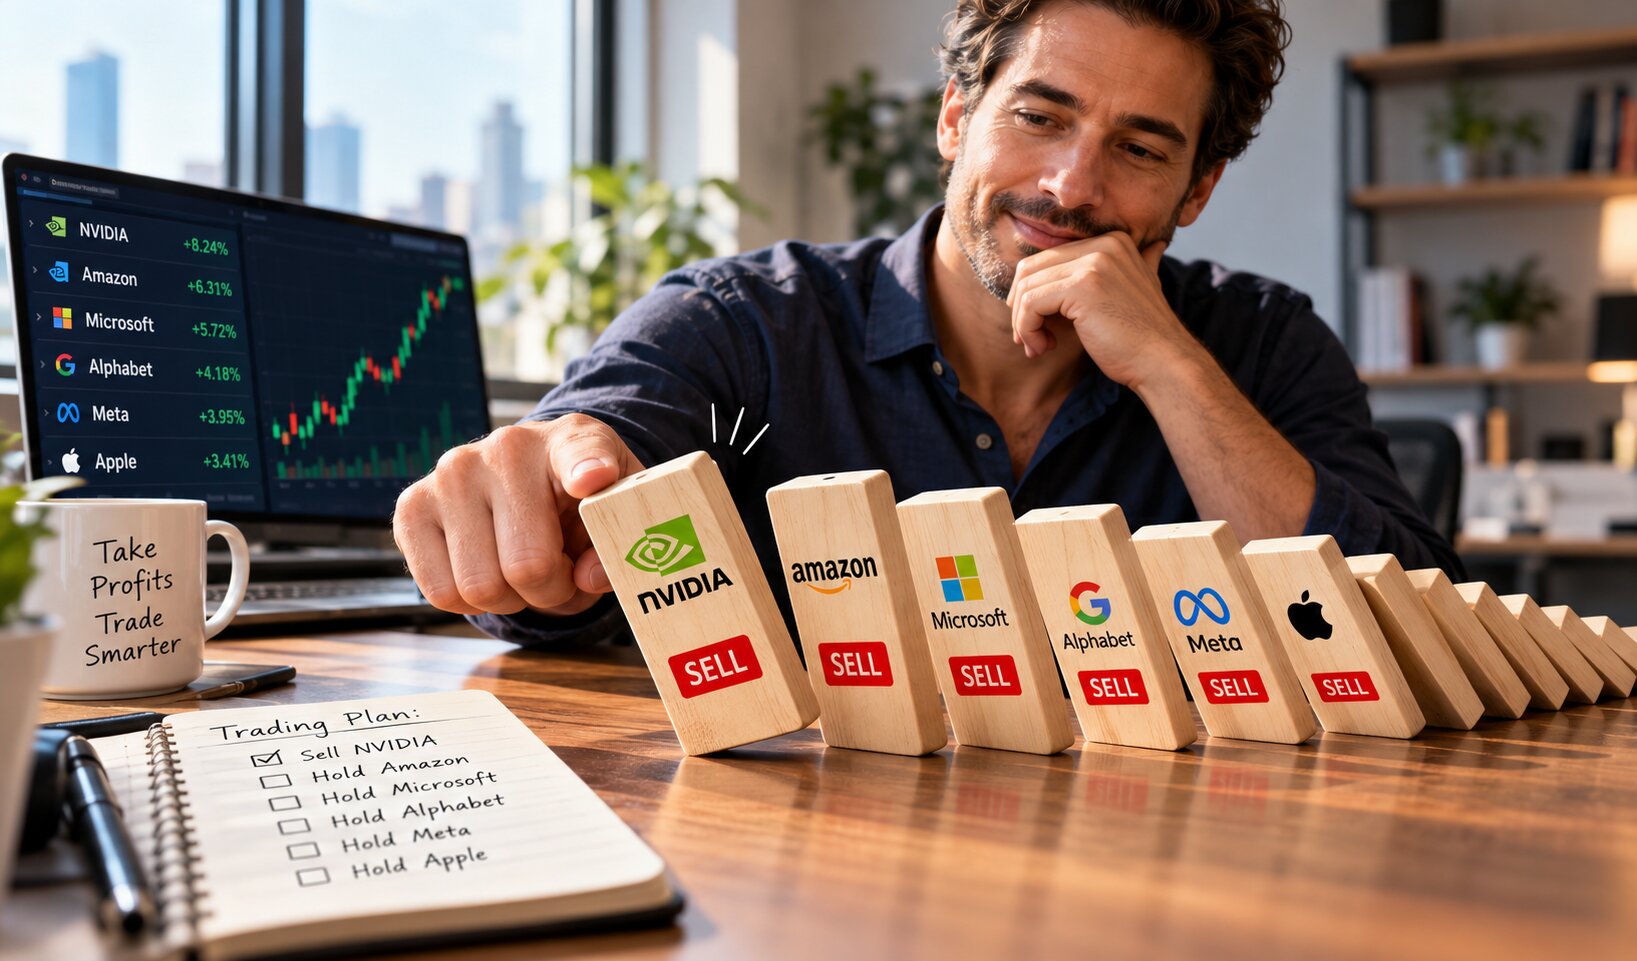
Consider this hypothetical portfolio:
| Stock | Original Intention | What Actually Happens |
|---|---|---|
| NVIDIA | Sell | Sold |
| Amazon | Hold | Sold |
| Microsoft | Hold | Sold |
| Alphabet | Hold | Sold |
| Meta | Hold | Held |
You initially intended to sell only NVIDIA.
But after executing that sale, you began reconsidering Amazon.
Then Microsoft.
Then Alphabet.
The interesting part is that your willingness to sell changed even though your original intentions for those stocks had not.
The first sale may have disrupted your preference for maintaining the status quo.
3. Realization Utility: Why Locking In Profits Feels So Good
Here’s another fascinating explanation.
Behavioral economists use the term realization utility to describe the psychological satisfaction investors can experience when converting unrealized gains into realized profits.
Imagine you purchase a stock for $100.
Its price rises to $150.
You now have a $50 unrealized gain.
But that gain exists only on paper.
When you finally sell the stock for $150, something psychologically significant happens.
The profit becomes realized.
You feel successful.
You made a profitable investment.
You locked in your gains.
You no longer need to worry about that particular profit disappearing in a market downturn.
Realizing a profit can create psychological satisfaction beyond the financial value of the transaction.
And this is where the domino effect may begin.
Once you’ve experienced that satisfaction, you may be tempted to repeat it.
You start looking at your other profitable investments.
Perhaps Amazon has an unrealized gain of $15,000.
Microsoft has another $10,000.
Alphabet has another $20,000.
Suddenly, those unrealized gains look like opportunities to experience the same satisfaction again.
You may find yourself selling not because the stocks are unattractive, but because realizing profits feels rewarding.
4. Positive Reinforcement: Your Brain Wants to Repeat a Rewarding Experience
Our brains learn from actions that produce rewarding experiences.
This is a fundamental principle of psychology called positive reinforcement.
When an action produces pleasure or satisfaction, we’re often motivated to repeat it.
Selling a profitable investment can produce several positive feelings.
You may feel accomplished because you made a successful investment.
You may feel relieved because you’ve protected your profits from a subsequent decline.
You may feel empowered because you’re actively managing your portfolio.
You may even experience a sense of control over an otherwise unpredictable financial market.
These feelings can make another profitable sale seem attractive.
But here’s the critical distinction.
Just because an action produces psychological satisfaction doesn’t mean repeating it is financially beneficial.
The future prospects of Microsoft have nothing to do with how satisfying it felt to sell NVIDIA.
Yet our minds can temporarily blur that distinction.
5. Mental Accounting: One Stock Sale Becomes a Portfolio-Wide Decision
Another possible explanation is mental accounting.
Mental accounting describes how people mentally organize and evaluate money, gains, losses, and financial decisions.
Before selling, you might evaluate each investment independently.
You consider NVIDIA based on its valuation.
Amazon based on its growth prospects.
Microsoft based on its earnings potential.
But after selling NVIDIA, your mental framework may change.
Instead of evaluating individual stocks, you start looking at your portfolio as a whole.
You might think:
“If NVIDIA is expensive, perhaps the other technology stocks are expensive too.”
“I’m sitting on substantial gains across my portfolio.”
“Maybe I should take profits while the market is still strong.”
Suddenly, what began as a decision about one company becomes a broader decision about your entire portfolio.
This is an example of shifting from narrow framing to wide framing.
Narrow framing involves evaluating investments individually.
Wide framing involves evaluating them in the context of the entire portfolio.
Neither approach is necessarily irrational.
In fact, evaluating portfolio-wide risk is often essential.
The potential problem arises when an unrelated trading decision triggers a portfolio reassessment that wouldn’t otherwise have happened.
6. Emotional Spillover: One Trade Changes Your Mood
Investment decisions are not purely mathematical.
They also involve emotions.
When you sell a profitable stock, you might experience relief, excitement, satisfaction, or a feeling of accomplishment.
Those emotions don’t necessarily disappear when you move on to evaluating another stock.
They can influence your next decision.
Psychologists refer to this general phenomenon as emotional spillover.
An emotion generated by one event can influence how we respond to another event.
In investing, this could work in several ways.
A profitable sale might encourage additional profit-taking because you feel successful.
A losing sale might increase anxiety and encourage you to reduce risk.
A particularly large gain might make you feel that you’ve accomplished your financial objective and should protect the rest of your portfolio.
The important point is that your emotional state can change even when the underlying investment opportunities remain unchanged.
This helps explain why your intentions before the first sale may differ significantly from your decisions afterward.
7. Action Bias: Doing Something Starts Feeling Better Than Doing Nothing
Investors sometimes experience action bias—a tendency to prefer taking action over remaining passive, even when inaction might be perfectly reasonable.
Before executing your first trade, you’re comfortable holding your investments.
But once you begin selling, doing something can start feeling more productive than doing nothing.
You may think:
“I’m actively managing my portfolio.”
“I’m protecting my profits.”
“I’m reducing unnecessary risk.”
“I’m being disciplined.”
These explanations might be entirely legitimate.
But there’s an important difference between selling because an investment no longer meets your criteria and selling because you’ve already started selling.
Action bias becomes potentially costly when activity itself begins to feel like progress.
Sometimes, the most sensible investment decision is to do absolutely nothing.
8. The Disposition Effect: Why Investors Prefer Selling Winners
Behavioral finance has extensively documented a phenomenon called the disposition effect.
It describes investors’ tendency to sell winning investments more readily than losing investments.
Why does this happen?
Selling a winner allows us to experience the satisfaction of being right.
Selling a loser forces us to acknowledge an unsuccessful investment.
Consequently, investors may be eager to realize gains while postponing the realization of losses.
This tendency can help explain why profitable positions become especially attractive selling candidates.
However, the disposition effect and the selling domino effect are not identical.
The disposition effect explains why investors often prefer selling winners. The domino effect concerns why one sale may be followed by several more.
The two tendencies can reinforce each other.
9. Psychological Closure: The Satisfaction of Cleaning Up Your Portfolio
There’s another interesting possibility.
Once you begin selling positions, you may develop a desire to simplify your portfolio.
You might find yourself thinking:
“I’ve already sold two positions. Perhaps I should close a few more.”
“Maybe I don’t need so many individual stocks.”
“Let me finish taking profits and start fresh.”
This can create a sense of psychological closure.
Just as completing a series of household chores can feel satisfying, closing several profitable investments can produce a feeling of accomplishment.
Your portfolio may feel cleaner, simpler, and easier to manage.
The satisfaction of completing a task can become another motivation for continuing to sell.
Of course, simplifying a portfolio can be a legitimate investment objective.
The question is whether simplification was part of your original plan or became appealing only after the first transaction.
10. Scientific Research: Investors Really Do Sell Multiple Stocks Together
Perhaps the most interesting aspect of this behavior is that researchers have documented something remarkably similar.
A 2021 study titled Wide Framing Disposition Effect: An Empirical Study, published in the Journal of Economic Behavior & Organization, examined trading behavior using historical brokerage data from American investors.
The researchers discovered that investors were substantially more likely to sell one stock on a day when they were already selling another.
In their sample of active traders, the baseline probability of selling a stock on days without other sales was approximately 1–2%.
On days when another stock was sold at a gain, the probability of selling an additional winning stock rose dramatically—to approximately 50% under the study’s measured conditions.
The researchers also observed that selling a losing stock increased the likelihood of selling a winning stock, and vice versa.
In other words, selling decisions often occurred together rather than as completely independent events.
The research doesn’t establish that the first sale psychologically caused the subsequent sales. Investors may also trade several stocks together because of market conditions, portfolio adjustments, or preexisting plans.
Nevertheless, the findings demonstrate that clustered selling is a real phenomenon in investor behavior.
A separate 2024 study published in The Journal of Finance, titled The Portfolio-Driven Disposition Effect, found that investors’ willingness to realize gains and losses also depends on the overall performance of their portfolios.
This provides further evidence that investment decisions are influenced not only by individual stocks but also by how investors mentally evaluate their entire portfolios.
11. Why the Domino Effect Can Be Financially Costly
Imagine you own five investments.
Each has an unrealized profit of $20,000.
You intend to sell just one.
But after taking that first $20,000 profit, you end up selling four positions.
You’ve now realized $80,000 in gains.
Naturally, you feel satisfied.
But consider what might happen next.
Suppose the three additional investments you hadn’t planned to sell subsequently appreciate another 25%.
You’ve missed that additional appreciation because you sold earlier than intended.
You may also have created unnecessary taxable gains in a taxable brokerage account.
Of course, the opposite could happen.
Those stocks might decline substantially, making your additional sales beneficial.
The real issue isn’t whether the market subsequently rises or falls. It’s whether each sale was supported by independent investment reasoning.
A favorable outcome doesn’t automatically prove that a decision was rational.
Likewise, an unfavorable outcome doesn’t necessarily mean it was irrational.
12. How to Prevent the Profit-Taking Domino Effect
The solution isn’t to stop taking profits.
It’s to recognize when your next decision is being influenced by your previous action.
Here are five practical techniques:
- Decide before you trade. Identify exactly which positions you intend to sell before executing your first transaction.
- Write down your reasons. Every planned sale should have a clear justification, such as valuation, changing fundamentals, portfolio concentration, or a predefined profit target.
- Recognize emotional momentum. If selling one stock makes you suddenly eager to sell others, acknowledge that your psychological state may have changed.
- Use the 24-hour rule. Consider postponing additional, unplanned sales until the following day, unless an urgent risk-management reason requires immediate action.
- Ask the independence question. Before selling another position, ask yourself: “If I hadn’t sold that first stock today, would I still want to sell this one?”
That final question may be the most powerful.
It helps separate an independent investment decision from one influenced by psychological momentum.
Final Thought: Sometimes the Market Hasn’t Changed. You Have.
We like to believe our financial decisions are driven by rational analysis.
We evaluate valuations, earnings, growth prospects, interest rates, and market conditions.
But our brains don’t process every decision in isolation.
Our previous actions influence our subsequent choices.
A profitable sale can produce satisfaction.
That satisfaction can encourage another sale.
The first transaction can break psychological inertia.
Breaking that inertia can make additional transactions easier.
And before we realize it, a carefully considered decision to sell one stock can become an unplanned liquidation of several investments.
The most fascinating part is that nothing about those other investments necessarily changed.
Their valuations didn’t change.
Their earnings prospects didn’t change.
Their long-term potential didn’t change.
The only thing that changed was our state of mind.
And that brings us to a fascinating lesson about human psychology and investing:
“Sometimes, the biggest influence on our next financial decision isn’t what the market just did. It’s what we ourselves just did.”
Understanding that distinction may be just as valuable as understanding the financial markets themselves.